Options Trading for Income: Strategies, Examples and Risks

Options trading for income means collecting premiums in exchange for taking on a defined obligation or market risk. The cash arrives when you sell the option, but your profit depends on what happens to the entire position afterward. This guide explains the main strategies, the capital they require, and how to evaluate results without mistaking a premium payment for a paycheck.
Key Takeaways
- Covered calls, cash-secured puts and credit spreads exchange different risks for a limited premium.
- Evaluate total profit and loss after closing costs, assignment, share-price changes and fees.
- Choose a position you can afford through an adverse move, then record whether its results justify the risk.
Build an options performance record
Financial Tech Wiz Trading Journal
Review recorded options positions by symbol, hold duration, day and time of day, with total P&L by option strategy.
Review your options results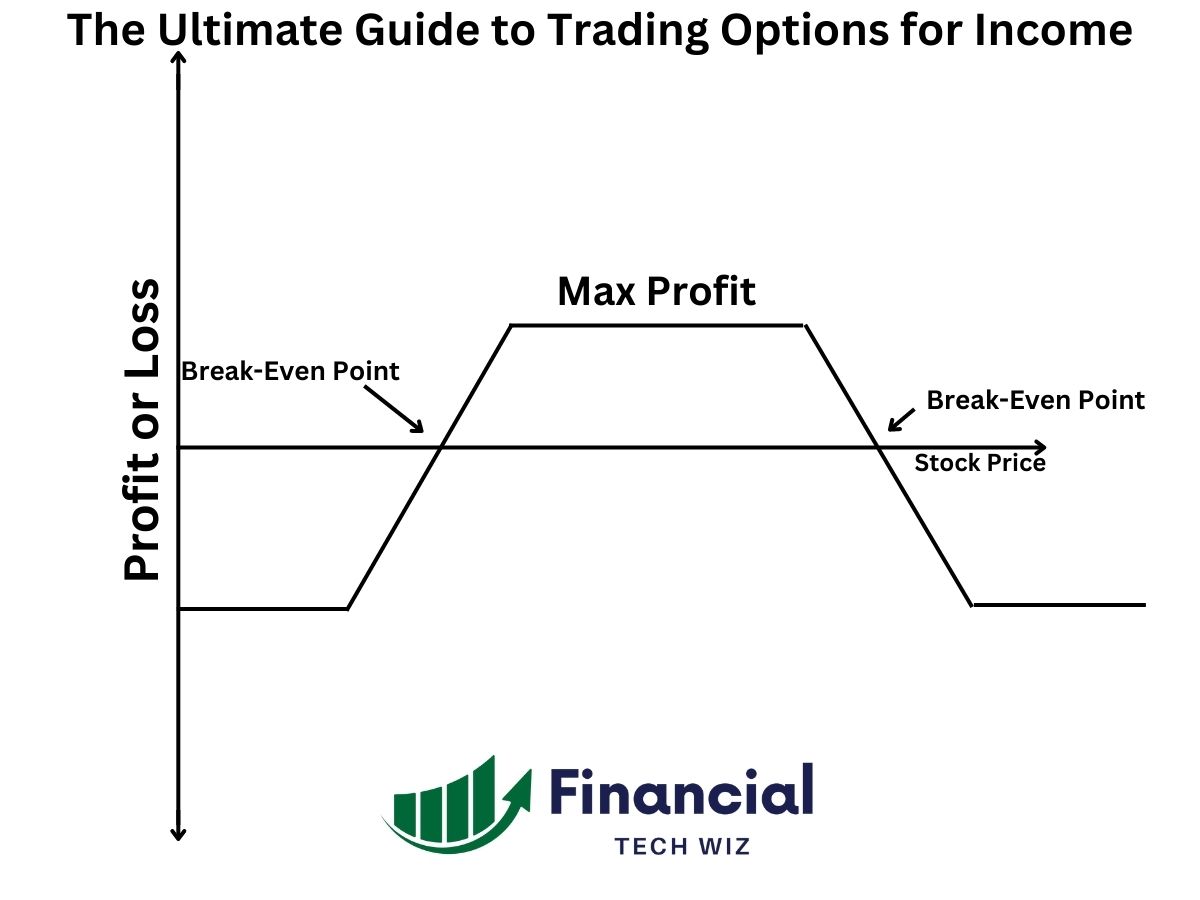
What options income actually means
When you sell an option to open a position, the buyer pays you a premium. In return, you accept the contract’s obligations. A short call can require delivering shares at the strike price; a short put can require buying shares at the strike price. Standard equity option contracts generally represent 100 shares, although adjusted contracts can differ.
That premium is a cash inflow, not an immediate economic gain. Your account also has an outstanding option liability. If you receive $150 and later pay $240 to close the option, the option trade loses $90 before fees. If it expires worthless, you retain the premium, but losses on associated stock can still outweigh it.
I find it more useful to evaluate an options trade as a complete position: what capital it ties up, what can go wrong, and what remains after every leg is closed. An attractive monthly premium does not establish a profitable strategy. It can simply reflect a stock with a large expected move or a position carrying substantial downside exposure.
For the broader framework, start with the options trading strategies guide. This article focuses on premium-selling decisions and the difference between cash flow and investment return.
Options terminology you need before selling premium
These examples assume standard contracts, no dividends and no transaction costs unless stated otherwise. They illustrate position mechanics rather than a recommended trade or expected return. Your account permissions, contract specifications and ability to manage the position still determine whether a structure is appropriate.
The strike price sets the transaction price specified in the contract. Expiration defines the contract’s final date, subject to its exercise rules and broker deadlines. The premium is the option’s market price. A quoted $1.50 premium ordinarily represents $150 for a standard 100-share contract, before commissions and other charges.
Intrinsic value is the amount an option is in the money. A call has intrinsic value when the stock price exceeds its strike; a put has intrinsic value when the stock is below its strike. Remaining premium is time value, also called extrinsic value. Out-of-the-money options have no intrinsic value, but their prices can increase sharply before expiration.
Sell to open creates a short option position. Buy to close removes that short position. Buying an option and later selling it is a different sequence: buy to open, then sell to close. Know which order you are submitting. Accidentally opening a new short contract instead of closing a long contract can change both your risk and your buying-power requirement.
Assignment means the option seller must fulfill the contract after an exercise is allocated to the position. American-style options can be exercised before expiration. European-style options follow different exercise rules. Cash-settled index options also differ from physically settled equity options. Verify the exact contract specification rather than applying a stock-option example to every product.
Compare the main options income strategies
| Strategy | Position | Main tradeoff | Capital or risk reference |
|---|---|---|---|
| Covered call | Own shares and sell a call | Limited upside, substantial stock downside | Share purchase cost less premium |
| Cash-secured put | Sell a put with cash reserved | Must buy shares if assigned | Strike obligation less premium |
| Credit spread | Sell an option and buy protection | Limited credit, defined expiration loss | Strike width less net credit |
| Iron condor | Combine put and call credit spreads | Needs a favorable price range | Wider spread width less net credit |
| Uncovered short options | Sell without sufficient offsetting coverage | Large losses and changing margin requirements | Not limited to the premium or opening margin |
The loss references above describe simplified expiration outcomes. Fees, early assignment, exercise decisions, liquidation and broken spread relationships can change the realized result. Defined-risk structures still need monitoring, especially near expiration. A broker’s opening buying-power requirement is not a promise about the largest loss you can experience.
Covered calls: premium in exchange for capped upside
A covered call pairs stock ownership with a short call against those shares. For a standard contract, you ordinarily hold 100 shares for each call sold. You receive a premium and agree to sell the shares at the strike if assigned. This structure fits an investor willing to sell at that price and still willing to own the stock if it declines.
Suppose you buy 100 shares at $50 and sell one $55 call for $1.50 per share. The stock costs $5,000 and the premium brings in $150. Ignoring fees and dividends, the combined expiration break-even is $48.50 per share. The maximum expiration profit is $650: $500 of stock appreciation to the strike plus the $150 premium.
If the stock finishes at $45 and the call expires worthless, the shares have lost $500 while the option contributes $150. The combined loss is $350. If the stock rises to $70, assignment at $55 generally limits the position’s expiration gain to $650. You received income, but surrendered the additional upside above the strike.
The premium provides a small buffer against a falling stock. It does not create a floor under the shares. In this example, a worthless stock would leave a $4,850 loss before fees. Avoid describing a covered call as safe simply because it is covered: coverage addresses the call delivery obligation, while the shares retain substantial market risk.
Before opening one, decide whether the strike is an acceptable sale price, whether an earnings release occurs before expiration, and whether an ex-dividend date could matter for early exercise. Read the dedicated covered call explanation for the mechanics behind the combined stock and option position.
Cash-secured puts: get paid for a purchase obligation
A cash-secured put involves selling a put while reserving enough cash to meet the assignment obligation. For one standard $50 put, the gross share-purchase obligation is $5,000. Your broker’s cash treatment can vary, but the trading decision should assume you may need to purchase all 100 shares at the strike.
Suppose you sell a $50 put for $2 per share and receive $200. If it expires out of the money, the option can expire worthless and you retain the $200 before fees. If you are assigned, you buy 100 shares for $5,000. The premium lowers the simplified economic break-even to $48 per share; it does not change the $50 contractual purchase price.
If the stock is worth $40 at expiration, shares acquired at $50 have a $1,000 loss offset by the $200 premium. The combined result is an $800 loss before fees. If the stock becomes worthless, the loss reaches $4,800. The put’s maximum profit is the $200 premium, while its potential loss is much larger.
Use the strategy only when the obligation fits your account and investment thesis. Wanting a stock at $50 today does not guarantee you will want it after disappointing earnings or a balance-sheet problem. The obligation remains even when your opinion changes. Review the cash-secured put mechanics before relying on assignment as your entry plan.
Credit spreads: smaller capital requirements with limited rewards
A put credit spread sells a higher-strike put and buys a lower-strike put with the same expiration. A call credit spread sells a lower-strike call and buys a higher-strike call. The purchased option limits the simplified expiration loss when the spread remains intact. A put credit spread typically expresses a bullish or neutral outlook; a call credit spread typically expresses a bearish or neutral outlook.
For example, sell a $50 put and buy a $45 put for a net credit of $1.20 per share. The spread is $5 wide. For one standard spread, the maximum expiration profit is $120 and the maximum expiration loss is $380 before fees: $500 of width minus the $120 credit. The expiration break-even is $48.80.
A $380 possible loss is more relevant than the attractive-looking $120 credit alone. Three $120 winners earn $360; one maximum loser costs $380. That sequence loses $20 before fees despite winning three of four trades. Win rate becomes meaningful only alongside average wins, average losses and the full distribution of outcomes.
Spread protection is not permission to ignore expiration. A short option can be assigned independently of the long option, creating a share position and additional operational exposure. Closing a spread before expiration can reduce that uncertainty, although available prices and liquidity still matter. Know your broker’s exercise deadlines and liquidation practices before opening the trade.
Iron condors and other premium-selling structures
An iron condor combines a put credit spread below the market with a call credit spread above it. Its best expiration outcome occurs when the underlying remains between the short strikes. With equal $5 wings and a $1 total credit, one standard condor has a $100 maximum expiration profit and a $400 maximum expiration loss before fees, assuming the position remains intact.
A short strangle sells a put and call at different strikes. A short straddle sells both at the same strike. Without protective options or appropriate stock coverage, losses can be very large; the short call side has theoretically unlimited loss. Opening margin can increase during an adverse move, forcing decisions at an unfavorable time.
A jade lizard combines a short put with a call credit spread. Some constructions collect enough credit to offset the call-spread width, but substantial put-side downside remains. A poor man’s covered call uses a long-dated call instead of shares against a shorter-dated short call. Different expirations, exercise risk and changes in time value make it more complex than owning stock.
You do not need to trade every structure. Begin with the position whose complete risk you can explain and whose capital requirement fits your account. A complicated trade can make it harder to identify why a result changed. Adding legs also adds transaction costs and execution decisions, even when it produces a more appealing payoff diagram.
Choose strikes and expirations around risk, not a cash target
Start with the price obligation you can accept. For a covered call, that means a strike where selling the shares fits your plan. For a cash-secured put, it means a purchase price and position size you can support. For a spread, start with a maximum loss that remains manageable if several positions move against you together.
Then compare expirations and their exposure to scheduled events. Shorter expirations can create faster changes in directional exposure as expiration approaches. Longer expirations keep capital committed for more time. An earnings release, product announcement or economic report can dominate both the premium and the subsequent price move. A larger credit around an event is compensation for uncertainty, not free extra yield.
Look at the bid-ask spread and available liquidity before estimating returns. A theoretical mid-price may not be executable. Opening a position near the ask and closing near the bid can consume much of a small credit. Use realistic assumed fills in a paper-trading record, and include commissions and contract charges when comparing two otherwise similar setups.
Avoid increasing the number of contracts merely to reach a desired monthly cash payment. Capital, diversification and loss tolerance set the position limit. The market does not owe you a particular premium at an acceptable risk. Some periods will offer no trade that meets your rules, and leaving capital uncommitted can be a valid outcome.
How implied volatility and the Greeks affect income trades
Implied volatility reflects the volatility embedded in option prices. Higher implied volatility often accompanies larger premiums, but also greater expected movement. IV rank compares current implied volatility with its range over a specified lookback; IV percentile uses a different comparison. Check which measure your platform displays and how it calculates the lookback before treating two readings as equivalent.
Delta measures an option price’s sensitivity to a change in the underlying, with other inputs held constant. Gamma measures how delta changes. Theta describes sensitivity to time passing. Vega describes sensitivity to implied volatility. These are model sensitivities, not a complete forecast of the trade or a guarantee that a position will behave the same way tomorrow.
A short option can benefit from time decay, yet lose money when the stock moves or implied volatility rises. Near expiration, directional changes can outweigh several days of collected decay. Likewise, a low-delta short option can still produce a substantial loss. Treat delta as one input rather than an exact real-world probability of a profitable result.
If you use TradingView to examine the underlying’s chart, keep that price analysis separate from the option chain, assignment rules and account risk. A chart signal alone does not establish whether a particular option is attractively priced. I may receive compensation if you purchase through this link.
Rolling a position does not erase a loss
Rolling means closing an existing option position and opening another, often at a different strike or expiration. It is two economic decisions even when your broker combines them in one order. You realize the old position’s result and accept the new position’s risk. A net credit on the combined order does not mean the original loss disappeared.
Suppose you sold a put for $150 and it now costs $400 to close. Closing realizes a $250 loss before fees. Selling a later put for $450 produces a $50 net cash credit on the roll, but leaves a new $450 option liability. The old $250 loss remains part of your trading record and the new contract still has to be managed.
Before rolling, ask whether you would open the replacement trade today without the original position. If the answer is no, extending the expiration may simply postpone an uncomfortable decision. Check total exposure, additional holding time, new event risk and the possibility of assignment. Compare rolling with closing, accepting assignment when appropriate, or reducing position size.
Evaluate return on capital without promising monthly income
A useful return calculation begins with a clearly defined numerator and denominator. Net realized profit divided by committed capital answers a different question from premium collected divided by broker margin. Label which one you use. Include the holding period and all relevant costs so that two trades can be compared on a consistent basis.
In the cash-secured put example, a $200 maximum premium against a $5,000 gross purchase obligation is 4% before fees for that contract’s holding period. It is not a promised monthly return. Assignment, a loss on the shares, a closing debit or unavailable future opportunities can change the outcome. Multiplying one favorable period by twelve ignores those differences.
A $1,000 monthly withdrawal from a $100,000 account equals 1% of starting capital for the month. That arithmetic says nothing about whether an options strategy can earn it consistently, what drawdown it may experience, or whether withdrawals will consume principal. Keep household obligations separate from speculative premium targets and evaluate a range of adverse outcomes before committing capital.
Use the options profit calculator to explore a position’s supported payoff scenarios, then compare those scenarios with the actual contract and broker requirements. A modeled payoff is useful for understanding the structure; it cannot establish the likelihood of a fill or remove execution, liquidity and assignment risk.
Plan for assignment before expiration week
Assignment should be part of the original plan, not a surprise you first investigate after a broker notification. For an equity put, ask whether the resulting share purchase would create an oversized position. For a covered call, decide whether selling the shares would disrupt another investment objective. In both cases, the acceptable answer depends on the whole account.
Do not assume an option must finish in the money at the regular-session close for assignment to be possible. Exercise decisions, broker deadlines and after-hours price moves can create uncertainty around expiration. A position close to a strike deserves particular attention. If you do not want the resulting shares or delivery obligation, evaluate closing the option while the market is open.
For a spread, know how you will respond if only one leg is exercised or assigned. The long option may still require a separate decision, and your account may temporarily hold stock exposure beyond the planned spread. Contact the broker for its specific handling rules before the situation occurs. A payoff diagram assumes a defined set of positions; it cannot manage those positions for you.
Keep enough available capital and time to manage the trade. Selling premium while unable to monitor expiration or respond to broker notices can create avoidable operational problems. A longer expiration does not eliminate that responsibility. Your trading schedule, account restrictions and comfort with share ownership should influence which contracts you consider in the first place.
Compare an income strategy with owning shares or holding cash
A strategy review needs an alternative. For covered calls, compare the complete position with owning the same shares without selling calls. Premium collection can help in some flat or declining periods, while the capped upside can cause the covered position to lag during a strong rally. Neither result is visible if you record only the option credits.
For cash-secured puts, compare the result with buying the shares immediately and with leaving the reserved capital uncommitted. A rising stock may leave you with a small premium while a shareholder participates in the rally. A falling stock may leave you assigned above its current market price. The comparison should reflect the objective you had before entering, rather than whichever alternative looks best afterward.
Cash treatment also matters. Determine whether reserved collateral earns interest, what your broker permits and how quickly funds are available after closing. Do not assume every account receives the same treatment. Keep any interest separate from options trading P&L when evaluating execution quality, then include it consistently when comparing total account outcomes over the same period.
Taxes can affect the amount available to spend, but the result depends on the instrument, jurisdiction and personal circumstances. Avoid treating an advertised premium yield as an after-tax return. Save trade confirmations and assignment records, and discuss your situation with a qualified tax professional when needed. This guide’s examples exclude taxes so their trading mechanics remain clear.
Use a review sample that includes difficult conditions
Ten quiet-market winners can create confidence without revealing how a strategy handles a gap or volatility spike. Review the conditions behind each result: trend, event exposure, holding period and the relationship between your positions. Separate the observation that recent trades worked from the stronger claim that the approach has a durable advantage across different markets.
A useful review compares average gains and losses, the largest losing period, time spent managing positions and the capital committed. Include trades you closed early and rolls that realized losses. Removing inconvenient outcomes makes the record less useful. Also distinguish a change in strategy from a change in market conditions before concluding that an adjustment improved performance.
Keep your testing assumptions conservative. A historical chart cannot prove that a multi-leg order would have filled at a convenient price. Paper results may omit slippage or the pressure of a live drawdown. Use the record to identify questions and improve decision rules, then continue checking those assumptions against actual execution instead of treating a backtest as a monthly income forecast.
Track the whole position and review the process
Record the underlying, strikes, expiration, contracts, opening credit, closing debit, fees and your original reason for entering. For a covered call, include the shares and their cost. For an assigned put, follow the resulting share position. Otherwise the option record can show a gain while the account bears a larger unrealized or realized stock loss.
Keep notes on earnings exposure, planned exits, assignment decisions and any roll. Those notes help explain whether a losing trade followed your rules or resulted from a preventable change in behavior. Review more than the largest winner. A strategy can collect small credits repeatedly while carrying losses that appear only during unusual market conditions.
The Financial Tech Wiz Trading Journal brings recorded trades and performance analytics together. Its Analytics tab shows win rate and P&L by day, time of day and trade duration, with a Position breakdown that includes total P&L by recorded option strategy. It does not provide win rate by expiration or by option strategy.
If you are starting with a spreadsheet, the free trading journal template provides an accessible place to build the recording habit. For a broader tool comparison, review the best trading journals. Whichever tool you choose, reconcile records against your brokerage statements and investigate missing legs before drawing performance conclusions.
Turn premium trades into reviewable data
Financial Tech Wiz Trading Journal
Compare recorded results and keep trade notes so your next review includes the losses, costs and decisions behind the credits.
See journal membership optionsA practical checklist before the next income trade
Write down the market outlook and why the selected structure expresses it. Identify the contract multiplier, settlement method and exercise style. Confirm that your broker permits the position, that you understand its buying-power treatment, and that the account can handle assignment or a difficult exit without depending on an immediate deposit.
Calculate the expiration maximum gain, break-even and loss reference using realistic fills. Then consider what happens before expiration: a price gap, wider bid-ask spreads, rising volatility or early assignment. Several positions in related stocks can lose together, so evaluate the combined portfolio rather than assigning each trade an isolated small risk budget.
Set review and exit rules before the trade becomes stressful. State the conditions that invalidate the thesis, how you will handle expiration, and what information would justify an adjustment. These rules do not guarantee an executable stop price. They give you a consistent basis for deciding and for evaluating the decision afterward.
After closing the position, compare the actual result with the plan. Separate market losses from execution mistakes, and avoid changing every rule after one outcome. A limited sample cannot prove an edge. Paper trading and small position sizes can support learning, but neither removes the possibility that future live results differ substantially.
FAQ
What is the best options strategy for income?
There is no single best strategy. Covered calls suit investors willing to sell shares at a chosen price; cash-secured puts suit investors able and willing to buy shares; credit spreads offer a defined expiration loss when intact. The choice depends on your outlook, capital, experience and ability to manage assignment and losses.
How do you trade options for income?
Choose a premium-selling structure, calculate the complete position’s risk, confirm the required capital and plan your exit before entering. Monitor the trade through closing, expiration or assignment. Record net profit and loss after costs rather than treating the initial premium as earned income.
Can selling options provide consistent income?
It can produce recurring premium receipts, but profits and available opportunities vary. A losing option or share position can outweigh several premium payments. There is no guaranteed monthly amount, and using leverage to meet a fixed income target can increase both drawdown and liquidation risk.
Is options trading a good way to make money?
Options can serve an investment or trading plan, but profitability requires more than selecting a high premium. You need an appropriate strategy, realistic execution assumptions and disciplined risk control. Some investors are better served by simpler positions. Evaluate suitability and results without assuming options will replace wages or produce passive income.
Financial Tech Wiz / Free resources
Build a clearer picture of your trading.
Start with the free trading journal template. Keep your trades organized, review your results, and build a consistent review routine.
- Free Google Sheets and Excel trading journal template
- Indicators, watchlists, and scanners
- Access to the free trading community
Ready for automatic trade tracking? Explore the Financial Tech Wiz Trading Journal.
Free resources + trading emails. Unsubscribe anytime.